
How to Use This Car Loan Calculator Canada
Our car loan calculator Canada tool is built for the way cars are actually bought here: with GST, HST or PST, trade-ins, dealer fees and bi-weekly pay cheques. You can use it for a new or used vehicle, dealer financing or a bank loan.
- Vehicle price – the negotiated price before tax.
- Down payment and trade-in – both lower the amount you borrow, and the trade-in also lowers the tax.
- Interest rate – the annual percentage rate (APR) from your lender.
- Loan term – anywhere from 12 to 120 months.
- Payment frequency – monthly, semi-monthly, bi-weekly or weekly.
- Province – sets the correct sales tax automatically.
Open More options to add dealer fees, money still owing on your trade-in, a cash rebate or extra payments. Then share your results with a link, print them, or download the full amortization schedule.
Car Loan Calculator Canada Formula, With an Example
Every auto loan calculator uses the standard amortization formula. In Canada, car loans compound at the same frequency as your payments, so the periodic rate is the APR divided by the number of payments a year.
- L = amount financed = price + fees + sales tax − down payment − trade-in + owing on trade-in − rebate
- r = APR ÷ payments per year (12, 24, 26 or 52)
- n = number of payments
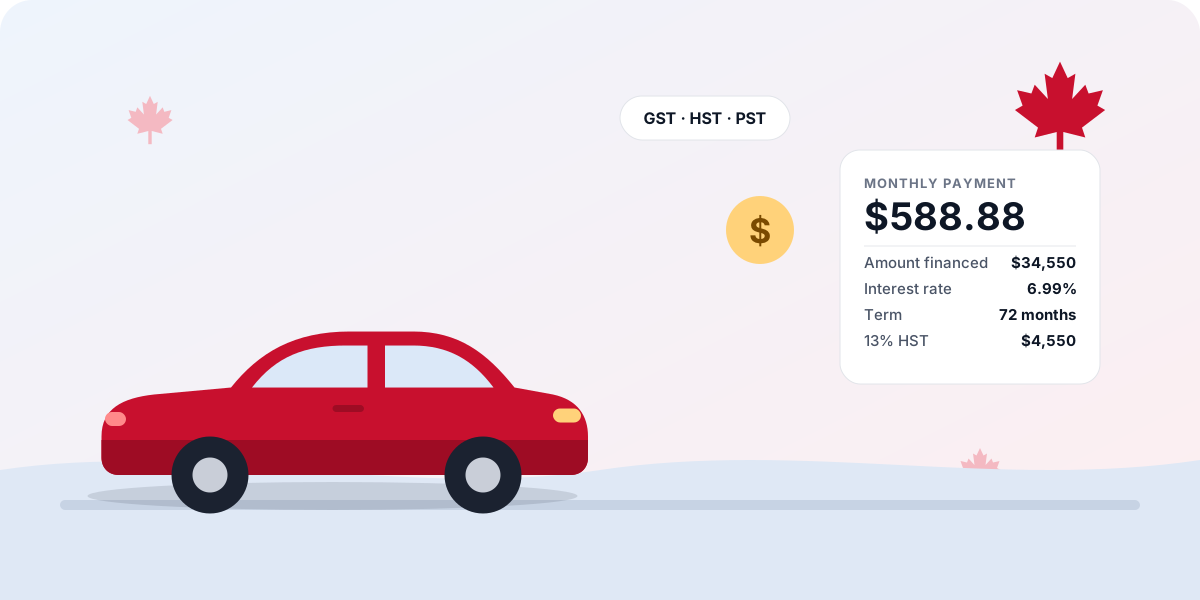
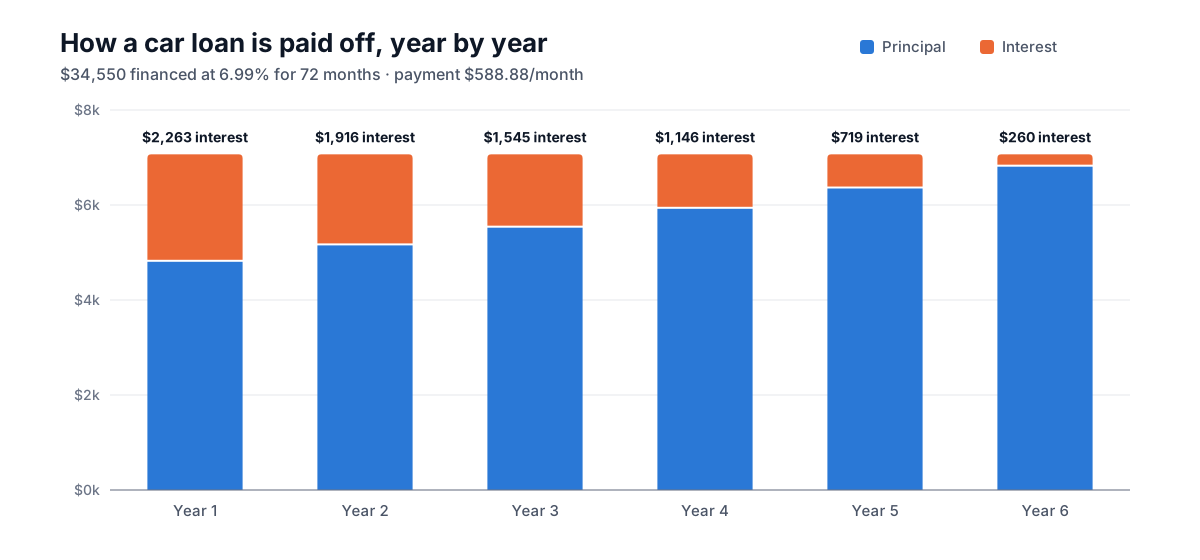
Example: a $35,000 car in Ontario with $5,000 down at 6.99% for 72 months. HST is 13% of $35,000 = $4,550, so L = $34,550. With r = 0.0699 ÷ 12 and n = 72, the payment is $588.88 a month, and you pay about $7,849 in interest over six years.
Want the same maths explained as an instalment? Read the car EMI calculator Canada guide.
Car Loan Calculator Canada: Sales Tax by Province
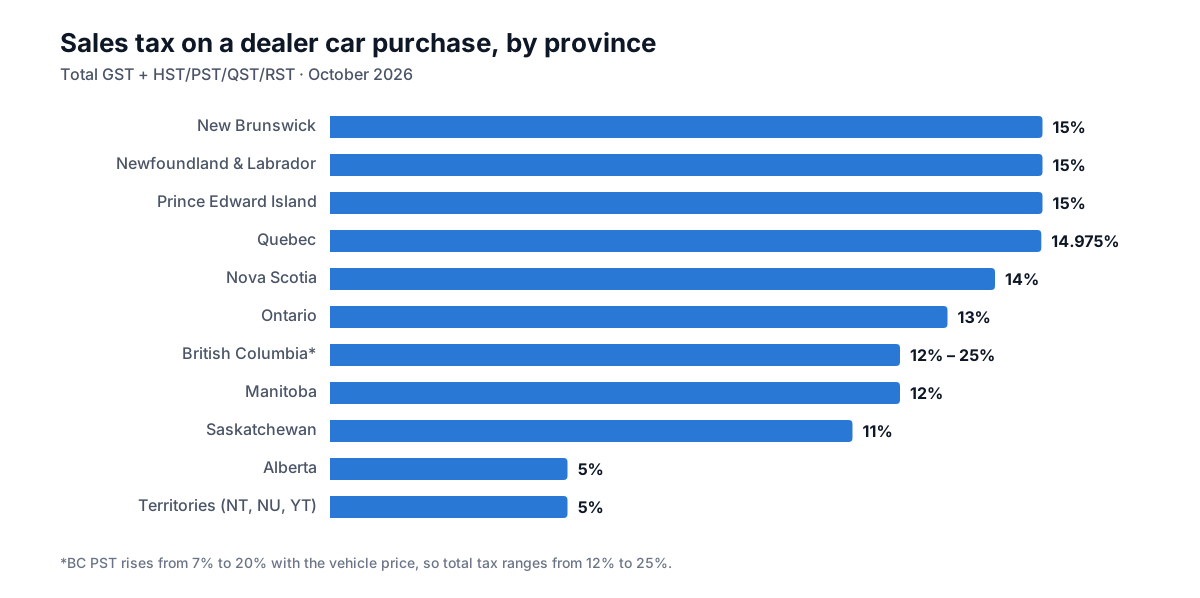
Sales tax is the biggest reason a US calculator gets your Canadian car payment wrong. This car finance calculator applies these rates for you:
| Province / territory | Tax on a dealer vehicle purchase | Total rate |
|---|---|---|
| Alberta | GST only | 5% |
| British Columbia | 5% GST + 7%–20% PST (tiered by price) | 12% – 25% |
| Manitoba | 5% GST + 7% RST | 12% |
| New Brunswick | HST | 15% |
| Newfoundland and Labrador | HST | 15% |
| Nova Scotia | HST (cut from 15% on April 1, 2025) | 14% |
| Ontario | HST | 13% |
| Prince Edward Island | HST | 15% |
| Quebec | 5% GST + 9.975% QST | 14.975% |
| Saskatchewan | 5% GST + 6% PST | 11% |
| Northwest Territories, Nunavut, Yukon | GST only | 5% |
Rates for dealer sales of passenger vehicles. Private sales, used vehicles, family gifts and electric vehicles can follow different rules in some provinces — check with your provincial registry before you buy.
On a dealer purchase, every province subtracts your trade-in before charging tax, and dealer admin fees are normally taxable. Province-specific guides: Ontario, British Columbia, Alberta and Quebec.
Car Loan Calculator Canada: Average Interest Rates in 2026
| Borrower / vehicle | Typical APR range |
|---|---|
| New car, manufacturer promotional financing | 0% – 4.99% |
| New car, excellent credit (bank or credit union) | 5.5% – 8.5% |
| Used car, good credit | 7% – 11% |
| Fair credit (roughly 600–680 score) | 10% – 16% |
| Bad credit / subprime lenders | 16% – 30% |
Illustrative ranges seen in Canada in late 2026, not quotes. Your rate depends on your credit score, income, debts, the vehicle's age and the loan term. Always ask for the APR in writing.
Even a couple of percentage points makes a big difference. Use the car interest calculator Canada to see how much each rate costs in dollars.
Choosing a Loan Term With the Car Loan Calculator Canada
The term is how many months you take to repay. Change it in the calculator and watch the Compare loan terms table:
- 36–48 months: higher payment, least interest, and you build equity fast.
- 60 months: a balanced choice for many buyers.
- 72 months: the most common term in Canada today.
- 84–96 months: lowest payment but the most interest, and a higher risk of negative equity.
Monthly vs. Bi-Weekly Payments
Dealers often quote bi-weekly payments because the number looks smaller. Twenty-six bi-weekly payments equal about 12 monthly payments, so the calculator shows a monthly equivalent to compare fairly. The car payment calculator Canada page covers every payment frequency in detail.
Car Loan Calculator Canada Tips: 7 Ways to Lower Your Payment
- Check your credit score and get pre-approved before you visit the dealer.
- Put 10%–20% down to avoid owing more than the car is worth.
- Negotiate the vehicle price first, then the financing.
- Compare a 0% promo against a cash rebate with the auto finance calculator.
- Don't roll negative equity from your old car into the new loan.
- Question add-ons such as extended warranties and rust-proofing that get added to the loan.
- Pay a little extra each period, if your loan allows it.
Car payments at popular price points
Real-world numbers for an Ontario buyer (13% HST) who puts 10% down and finances the rest at 6.99% for 72 months. Use these to sanity-check a dealer quote, then enter your exact deal in the calculator above.
| Vehicle price | 10% down | Amount financed | Monthly | Bi-weekly | Total interest |
|---|---|---|---|---|---|
| $25,000 | $2,500 | $25,750 | $438.89 | $202.31 | $5,850 |
| $30,000 | $3,000 | $30,900 | $526.67 | $242.77 | $7,020 |
| $35,000 | $3,500 | $36,050 | $614.44 | $283.23 | $8,190 |
| $40,000 | $4,000 | $41,200 | $702.22 | $323.69 | $9,360 |
| $50,000 | $5,000 | $51,500 | $877.78 | $404.62 | $11,700 |
| $60,000 | $6,000 | $61,800 | $1,053.33 | $485.54 | $14,040 |
Tax is applied to the full price; the down payment is subtracted after tax. Fees and trade-ins are not included.
New vs. used car loans in Canada
| New vehicle | Used vehicle | |
|---|---|---|
| Typical rate | 0%–8.5% (promos available) | 7%–11%+ for good credit |
| Longest common term | 84–96 months | Often 60–84 months, shorter for older cars |
| Who lends | Manufacturer finance arms, banks, credit unions | Banks, credit unions, dealer lenders |
| Depreciation | Fastest in the first 2–3 years | Slower — someone else took the biggest hit |
| Tax | Dealer: GST/HST/PST | Dealer: same; private sale rules vary by province |
A used car usually costs less to buy but more to borrow for. Compare a new car at a promo rate with a two- or three-year-old model at a bank rate — the total cost is often closer than the sticker prices suggest.
Negative equity: the trap of rolling over a loan
Negative equity means you owe more on your car than it's worth. It's common with long terms and small down payments, because cars lose value faster than the balance falls in the first few years.
Example: you owe $18,000 on a car worth $14,000. The dealer rolls the $4,000 difference into your new loan. At 6.99% over 72 months, that adds about $68.18 to every monthly payment and $909 in extra interest — for a car you no longer own. Enter the numbers under More options → Owing on trade-in and the calculator will flag it.
To avoid it: put at least 10%–20% down, choose a term of 60 months or less if you can, and keep your car until the loan is paid off or close to it.
Lease or finance? A quick Canadian comparison
| Financing (car loan) | Leasing | |
|---|---|---|
| You own the car | Yes, once paid off | No — return it or buy it out |
| Monthly payment | Higher | Lower for the same car |
| Mileage limits | None | Usually 16,000–24,000 km/year, with excess charges |
| Tax | Paid on the full price (usually financed) | Paid on each lease payment |
| Best for | Keeping a car 6+ years, high mileage | A new car every 3–4 years, predictable driving |
Financing usually costs less over the long run if you keep the vehicle after the loan ends — years with no payment at all.
What Canadian lenders look at
- Credit score. Scores above roughly 700 usually get the best rates; below about 600 you may be limited to subprime lenders.
- Debt-service ratios. Lenders compare your monthly debt payments, including the new car loan, with your gross income. Keeping total debt payments under about 40% of gross income helps approval.
- Income and job stability. Expect to show recent pay stubs or, if self-employed, notices of assessment.
- Down payment and the vehicle. More money down and a newer vehicle lower the lender's risk and can lower your rate.
The real monthly cost of owning a car
Your loan payment is only part of the bill. Before you settle on a budget, add:
- Insurance — often the second-largest cost, and highest in Ontario and BC.
- Fuel or charging — based on your commute and the vehicle's efficiency.
- Maintenance and tires — winter tires are required in Quebec from December 1 to March 15 and on many BC highways from October 1 to March 31.
- Registration, licence and parking.
The car payment estimator helps you work backwards from a total budget that includes these costs.
Checklist before you sign a car loan
- Confirm the APR, term and payment frequency match what you agreed.
- Check the amount financed — price, tax, fees, trade-in and down payment should add up. Recalculate it here.
- Look for add-ons you didn't ask for and remove them.
- Ask whether you can prepay without penalty.
- Get the total cost of credit in writing — Canadian lenders must disclose it.
- Keep a copy of the signed bill of sale and credit agreement.
Car loan glossary
- APR
- Annual percentage rate — the yearly cost of borrowing, including certain fees. The best number to compare loans.
- Amortization
- Paying off a loan through regular payments that cover interest first, then principal.
- Amount financed
- What you actually borrow after tax, fees, down payment and trade-in.
- Principal
- The part of the balance that isn't interest.
- Term
- How long you have to repay, in months.
- Negative equity
- Owing more on a vehicle than it's worth.
- Trade-in tax credit
- On a dealer purchase, sales tax is charged only on the price after your trade-in.
- Open loan
- A loan you can pay off early without a penalty — most Canadian car loans are open.
Car Loan Calculators by Province
Car Loan Calculator Canada – Frequently Asked Questions
How do I calculate a car loan payment in Canada?
Add the vehicle price, taxable dealer fees and your province's sales tax, then subtract your down payment and trade-in. That gives the amount financed. Put the amount, your APR and the term into the formula P = L × r ÷ (1 − (1 + r)−n), or simply type the numbers into the car loan calculator Canada tool above.
Is sales tax included in a car loan in Canada?
Usually, yes. Canadian dealers normally add GST, HST or PST to the price and you finance the total, so you also pay interest on the tax. The calculator adds the right tax for your province; untick “Add sales tax” if you will pay it in cash.
Does a trade-in reduce sales tax in Canada?
Yes, when you buy from a dealer. Every province deducts the trade-in value before charging tax. In Ontario, a $10,000 trade-in saves $1,300 in HST. Private sales do not get this credit.
What is a good car loan interest rate in Canada?
In late 2026, buyers with strong credit typically see 5.5%–8.5% from banks and credit unions, and new-car promotions can be 0%–4.99%. Used vehicles and lower credit scores push rates higher. Try different rates in the car interest calculator.
What is the longest car loan term in Canada?
Most lenders go up to 84 months, and some offer 96 months. Longer terms lower your payment but add a lot of interest and raise the risk of owing more than the car is worth.
Are bi-weekly car payments better than monthly?
Bi-weekly payments match many Canadian pay cycles, but at the same rate and term they cost about the same in interest as monthly payments. See the car payment calculator Canada page for a side-by-side comparison.
Can I pay off a car loan early in Canada?
Most Canadian car loans let you prepay without penalty, but read your contract. Enter an amount in “Extra per payment” to see how much interest you save.
Is this car loan calculator free?
Yes. It is free, needs no sign-up and runs entirely in your browser, so the numbers you enter stay private.
More car loan calculators for Canada
All results are estimates for information only. Your lender sets your final rate, payment and fees. Read our disclaimer.